Intel

Featured
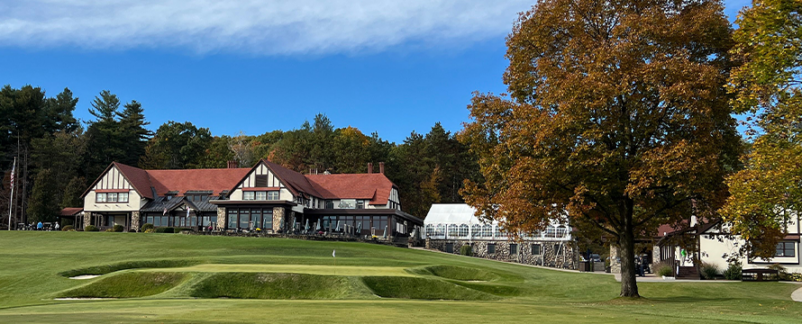
Century-Old Clubhouse Destroyed by Fire Faces Complex Rebuild
Inside This Article: A fire recently destroyed the historic Lochmoor Country Club clubhouse in Grosse Pointe Woods, Michigan. Historic properties may require specialized Commercial Property Insurance with Historical Replacement Cost to reproduce original materials, designs, and craftsmanship after a loss. Business Interruption Coverage and Extra Expense Coverage can help companies recoup lost revenue and maintain payroll during restoration. Updates
$25.6 Billion in Nuclear Verdicts Raises Stakes for Businesses
Inside This Article: “Nuclear” verdicts increased 40.7% in 2025, reaching their highest annual total since 2009, according to Marathon Strategies. The nearly 200 verdicts of at least $10 million in 2025 totaled approximately $25.6 billion. Claims that have previously stayed within primary insurance limits are increasingly reaching Excess Liability Insurance layers. Business owners are encouraged to closely review policy
In the News




Trending
Other Recent Intel

A subsidence claim does not always require contractor negligence to become a coverage issue. In this clip from our recent Construction Insurance webinar, Alex Fifelski, Broker, Burns & Wilcox, Brokerage Division, Atlanta, Georgia, explains how subsidence exclusions can leave contractors exposed when earth movement contributes to a loss. https://vimeo.com/1202183081/3ca2a457b1?share=copy&fl=sv&fe=ci

One of the most dangerous construction coverage gaps can be hidden in the fine print. In this clip, David Gross, Vice President, Managing Director, Broker, Casualty, Burns & Wilcox, Brokerage Division, North Dallas, TX, highlights the risks behind Action Over claims and why a closer review of endorsements can help uncover issues before they turn into serious problems. https://vimeo.com/1202181526/43de2cc8ef?share=copy&fl=sv&fe=ci

Why It Matters: Many homeowners know their home\'s market value but may not understand what it would cost to rebuild it. Knowing replacement cost estimates can help determine the amount of insurance needed to repair or rebuild a home after a covered loss. Rising construction costs, evolving building codes, and home improvements can all increase rebuilding expenses. Additionally, increased demand following a catastrophic event—such as a hurricane, flood, or wildfire—may drive costs even higher. These factors can create potential…

Scenario 1: A coastal community is hit by a hurricane, leaving many homes and businesses with extensive wind damage and flooding. RELATED STATS: Hurricane impacts can range from minor wind damage on a roof to a total loss, especially in cases of catastrophic flooding. U.S. homeowners collectively spend approximately $20 billion per year repairing their homes after storms. SOLUTION: Homeowners…

Inside This Article: A proposed class-action lawsuit alleges a popular tomato brand misled consumers about the authenticity of its San Marzano tomatoes. While the brand has called the claims meritless, even unproven allegations can lead to significant legal expenses and reputational damage. Commercial General Liability (CGL) Insurance can help cover expenses associated with advertising-related lawsuits, while Excess Liability Insurance can provide additional protection. Companies…

Seemingly minor changes in policy language can create significant coverage gaps for Construction risks. In this webinar, Burns & Wilcox experts discuss key terms, conditions, and exclusions that can influence underwriting decisions and claim outcomes, including action-over, subcontractor exclusions, hot work operations, subsidence exposures, residential limitations, and work height restrictions. Featured experts: David Gross, Vice President, Managing Director, Broker, Casualty, Burns &…
Powered by